THE BANK MANAGER WHO MOCKED A POOR FARMER
THE BANK MANAGER WHO MOCKED A POOR FARMER
He Tried to Take His Ranch—Until a Thirty-Year-Old Secret Came Back to Haunt Him
PART 1 — “YOU CAN’T AFFORD THIS BANK”
The snow had been falling over Red Hollow, Montana, since before sunrise.
By eight-thirty that morning, the small town’s brick sidewalks had disappeared beneath a layer of white, and the wind sweeping down from the mountains had turned the streets into empty corridors of ice. Pickup trucks moved slowly past closed storefronts. Smoke curled from chimneys. Beyond the town limits, cattle huddled behind windbreaks, waiting for the storm to pass.
Inside Red Hollow Community Bank, the heating system hummed quietly beneath the glow of vintage brass lamps. The building had once been a general store, and its original red-brick walls had been preserved when the bank renovated it. Dark walnut counters stretched across the lobby, while tall industrial windows overlooked the snow-covered street.
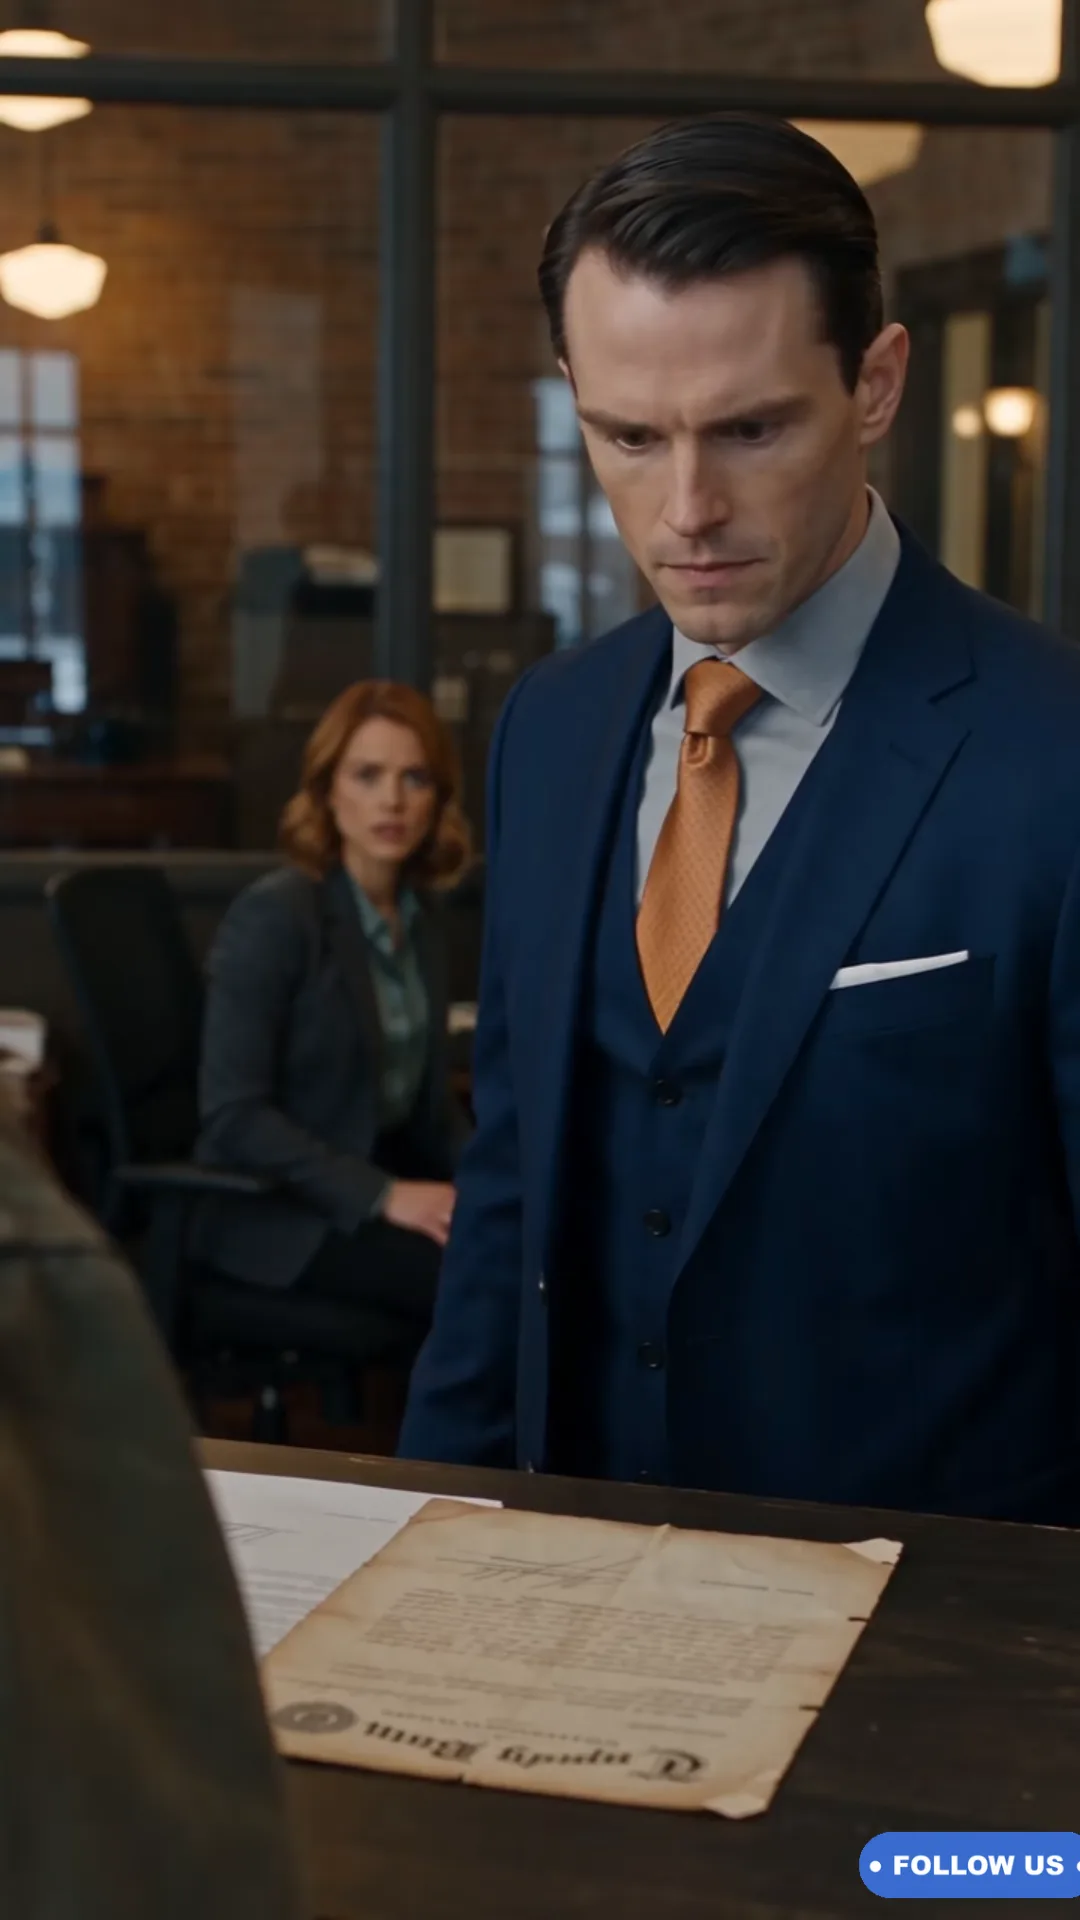
Behind one of those counters stood Victor Hale, the bank’s forty-eight-year-old manager.
His midnight-blue suit looked as if it had been tailored around his ambition. His copper-colored tie was perfectly centered, his black shoes gleamed beneath the counter, and his slicked-back hair showed not a strand out of place.
Victor liked things orderly.
He liked clients who arrived in expensive vehicles, wore polished shoes, and addressed him with the proper degree of respect. He liked business owners who understood that money spoke louder than promises.
Most of all, he liked being the man who decided who deserved a second chance.
At 8:37 a.m., the front door opened.
A gust of freezing air entered the lobby, followed by an elderly man wearing a faded forest-green ranch coat. One cuff was torn, his tan leather boots were scuffed, and a dark-brown cowboy hat rested low over his forehead. A cracked leather satchel hung from his shoulder.
Franklin Walker, known throughout the county as Frank, paused to brush snow from his coat.
He was seventy-one years old. His shoulders had begun to stoop, his face was marked by decades of wind and sun, and his silver-white beard framed a mouth that had learned to remain closed when anger would accomplish nothing.
He approached the counter slowly.
Victor glanced at him, then at the satchel.
“Can I help you?” he asked without warmth.
“I have an appointment about my ranch loan.”
Victor tapped a few keys.
“Name?”
“Franklin Walker. Walker Ranch.”
The manager’s fingers stopped.
He looked at the screen again, then leaned back in his chair.
“Oh,” he said. “You.”
Frank did not react.
“I was told to come in before the end of the week.”
“You were told to come in because your account is delinquent.”
“I know what I owe.”
“Do you?” Victor asked, raising an eyebrow. “Because according to these records, you’ve missed several payments.”
“The cattle market dropped. Then the winter feed costs went up. I sold what I could without cutting the herd below a number I can rebuild from.”
Victor gave a short laugh.
“That sounds like a rancher’s way of saying he doesn’t have the money.”
Frank tightened his hand around the satchel strap.
“I’m asking for thirty more days.”
“Thirty days?” Victor repeated, loud enough for the woman working at the records desk to hear. “What exactly do you think will happen in thirty days? The cattle will start printing money?”
A flush crept up Frank’s weather-beaten cheeks, but he kept his voice steady.
“I’ve got a buyer interested in part of the herd. The agreement is being finalized. If I can complete the sale, I can bring the loan current.”
Victor slid a document across the counter.
“This is the final notice. The bank has already initiated foreclosure proceedings.”
Frank looked down at the paper.
He had known the day might come. He had spent the previous six months rearranging bills, delaying repairs, selling equipment, and negotiating with buyers. He had eaten less, slept less, and worked through storms that would have kept younger men indoors.
But he had never imagined that the last conversation about his family’s land would happen in a room where a man in a perfect suit could barely be bothered to look him in the eye.
“The loan was taken out against the cattle and the equipment,” Frank said. “The land was supposed to be protected under the original agreement.”
Victor’s expression changed.
Only slightly.
A quick narrowing of the eyes. A pause just long enough to be noticed by someone who had spent a lifetime reading the weather.
Then the smirk returned.
“Whatever you think was promised to you, Mr. Walker, the bank’s records are clear.”
“I’d like to see the original file.”
“You don’t need to see anything. You need to pay what you owe.”
“I’m asking for a review.”
“And I’m telling you that your ranch is finished.”
Victor stood and gestured toward the entrance.
“Leave.”
The word struck the lobby harder than a shout.
Frank remained still.
Behind the records desk, Claire Bennett slowly lifted her head.
At thirty-two, Claire had worked at Red Hollow Community Bank for nearly six years. Her job involved loan records, archived agreements, title documents, and the details other people considered too tedious to examine. She knew that a clean spreadsheet could conceal a disastrous decision, and she had learned to pay attention when someone tried too hard to end a conversation.
She had been listening to every word.
“Victor,” she said carefully, “I can review Mr. Walker’s file before we proceed.”
Victor turned toward her.
“That account is restricted.”
“I understand. But if there’s a question about the collateral—”
“There isn’t.”
Claire glanced at the screen in front of her.
“Then it should only take a few minutes to confirm.”
Victor’s jaw tightened.
“I said no.”
Frank looked from one employee to the other.
He had not come to the bank expecting kindness. He had come because a promise had been made to his father long before either Claire or Victor worked in the building.
Now the manager was refusing to examine the very agreement that might explain why the bank’s foreclosure paperwork did not match what Frank remembered.
He slowly lowered his satchel onto the counter.
“Thirty days,” he repeated. “That’s all I need.”
Victor shook his head.
“You can’t afford this bank.”
Frank looked directly into his narrow eyes.
“Maybe you should find out what your bank can afford to lose.”
For the first time that morning, Victor did not answer immediately.
Then he laughed again.
“Get out.”
Frank picked up his satchel.
He turned toward the door, but he did not leave.
Instead, he stepped to the side of the counter and waited.
Claire saw something in his face that did not belong to a desperate borrower.
It was not panic.
It was not confusion.
It was the expression of a man who had spent years hoping he would never need to use something he had been carrying for a very long time.
And when Victor turned back toward his office, Frank quietly unfastened the satchel.
Inside was an envelope wrapped in brown paper.
The edges were worn. The string around it had darkened with age.
On the front, written in faded blue ink, were four words:
THE ORIGINAL LAND AGREEMENT.
Frank closed the satchel again.
He would wait a little longer.
Because thirty years of silence were about to end.
PART 2 — THE FILE THAT SHOULD NEVER HAVE EXISTED
Claire waited until Victor disappeared into his glass-walled office before turning back to her computer.
Frank remained near the counter, watching the snow drift against the windows.
She opened the bank’s internal loan system and entered his account number. A series of ordinary records appeared: payment histories, equipment valuations, insurance documents, notices of default, and a foreclosure authorization.
At first glance, everything seemed straightforward.
The loan was behind schedule. The bank had issued warnings. The required payments had not been made.
But Claire noticed a discrepancy.
The foreclosure authorization referenced a separate property instrument dated June 14, 1996.
Its classification was unusual. Instead of appearing under the normal land-collateral category, it was marked as a restricted legacy agreement. Access had been limited to senior management and the bank’s legal department.
The file had been opened three months earlier.
It had also been modified twice.
Claire frowned.
She checked the document history. The first entry showed a review by Victor Hale. The second recorded an authorization that appeared to release certain restrictions on the Walker property.
The electronic signature looked like Victor’s.
The attached approval, however, carried the name of a former bank executive who had died years earlier.
Claire sat motionless.
She enlarged the scanned signature.
The letters were similar, but the final stroke was wrong. She had seen thousands of signatures in her work. She knew that people changed the way they wrote their names, but this was not a natural variation. It looked as if someone had copied the shape rather than written the name.
She opened the archived correspondence attached to the file.
There was a note from the bank’s former legal department:
Original covenant required before any transfer, sale, or foreclosure affecting protected acreage.
Below it, another note had been added in recent months:
Original unavailable. Proceed using digital authorization.
Claire read the lines again.
The original agreement had not been declared lost thirty years earlier. The bank’s own system indicated that it had been required for a current transaction.
Someone had simply decided that its absence no longer mattered.
She looked through the glass wall of Victor’s office.
He was standing beside his desk, speaking on his mobile phone. His back was turned to the lobby. His left hand moved sharply as he spoke, and his face had lost the relaxed confidence he had displayed at the counter.
Claire could not hear the conversation.
She returned to the file.
A development company appeared in the foreclosure notes: Granite Peak Development Group.
The company had recently acquired several parcels near Red Hollow, including land along the highway that connected the town to a planned regional industrial corridor. Local residents had heard rumors of a large commercial project, but no official announcement had been made.
The notes indicated that Granite Peak had expressed interest in acquiring the Walker Ranch property.
The price listed in the preliminary valuation was substantially higher than the amount needed to settle Frank’s debt.
Claire sat back.
The bank was not merely trying to recover a delinquent loan.
It appeared to be moving toward a sale that could generate a significant profit, provided the restrictions on the land were removed.
And the suspicious signature was the key to that removal.
She picked up the desk phone.
“Compliance department, please,” she said when the call connected. “This is Claire Bennett at Red Hollow Community Bank. I need an urgent review of a foreclosure authorization.”
A voice asked for the account details.
Claire supplied them.
Then she lowered her voice.
“The authorization references a legacy covenant dated 1996. The original is missing from the bank file, and the digital approval contains a signature that may not be authentic.”
She listened.
“No, I haven’t approved anything. I’m asking for the transaction to be paused until the original document can be examined.”
The office door opened.
Victor stepped out.
“What are you doing?”
Claire covered the receiver.
“Requesting a compliance review.”
His expression hardened.
“I told you that account was restricted.”
“And I found a discrepancy in the authorization.”
“You found an old record you don’t understand.”
“I understand the signature doesn’t match the other approved documents.”
Victor walked toward her desk.
“Put that phone down.”
Claire did not move.
“Victor, if the authorization is valid, a review will confirm it.”
“Do you have any idea what you’re doing to this bank?”
“I’m trying to make sure we don’t foreclose on property using a document that may be forged.”
His face went pale.
For a moment, he looked less like a manager and more like a man who had just heard a locked door open behind him.
Then he glanced toward Frank.
The old rancher had not moved from the counter.
Victor returned his attention to Claire.
“You will end that call,” he said quietly, “and you will not access that file again.”
Claire’s fingers tightened around the receiver.
“No.”
The word surprised both of them.
Victor leaned closer.
“Excuse me?”
“You heard me.”
“You’re an employee of this bank.”
“And this is a bank record. If the approval is false, burying it won’t make it legitimate.”
Victor straightened.
“You have no proof.”
“Then let compliance investigate.”
He stared at her, searching for hesitation.
He found none.
With a sharp movement, he reached toward the phone.
Claire pulled it away.
Frank spoke for the first time since opening his satchel.
“Careful, son.”
Victor turned.
“Stay out of this.”
“I’ve stayed out of it for thirty years.”
Frank unfastened the satchel.
“And that was my mistake.”
He removed the brown-paper envelope and placed it on the counter.
The old paper made a soft sound against the walnut.
Victor stared at it.
The color drained from his face.
Frank untied the string.
Inside lay an aged cream-colored document, its edges fragile but intact. Faded blue ink crossed the page. An embossed circular bank seal rested near the bottom, beside handwritten signatures.
The document was not a copy.
It was the original.
Victor took a step backward.
Frank laid the paper flat.
“You made one mistake,” he said.
Victor’s mouth opened, but no words came out.
Frank’s voice remained steady.
“You never checked who owned this land.”
Claire looked at the document, then at her computer.
The name on the screen matched the name on the original.
But the ownership provision did not match the foreclosure authorization.
Frank looked directly at Victor.
“You tried to steal it.”
For the first time, the bank manager seemed unable to decide whether to shout, run, or pretend the document did not exist.
Then Claire saw the signature beneath the embossed seal.
And she recognized the surname.
Hale.
PART 3 — THE PROMISE MADE IN 1996
Thirty years earlier, Walker Ranch had been a very different place.
Frank was forty-one then, with stronger knees, darker hair, and a wife who laughed loudly enough to carry across an entire field.
His wife, Margaret, had grown up in Red Hollow. She knew every family in town, remembered birthdays without writing them down, and believed that a promise mattered most when keeping it became inconvenient.
Together, Frank and Margaret had worked the ranch through droughts, cattle disease, equipment failures, and winters when the snow covered the fence lines for weeks.
The ranch had belonged to Frank’s family for generations.
It was not the largest operation in Montana, but it had good grazing land, a reliable water source, and a stretch of protected acreage along the northern boundary. The protected section mattered because the Walker family had agreed to preserve the natural spring and the surrounding watershed. The water fed a small creek that ran through several neighboring properties before reaching the valley.
Frank’s father had believed the spring was a gift that belonged to everyone who depended on it.
Frank had inherited that belief.
In 1996, a severe financial crisis nearly destroyed the ranch.
A combination of drought, falling cattle prices, and unexpected medical expenses left Frank struggling to pay suppliers. The local bank at the time was managed by Thomas Hale, Victor’s father.
Thomas was a careful man, known for carrying a small notebook in his jacket pocket. He had worked at the bank for more than twenty years and understood that rural customers often possessed valuable assets but little immediate cash.
He knew Frank’s father.
He knew the ranch.
And he knew that selling the property to satisfy a short-term debt would damage more than one family.
One afternoon, Thomas visited the ranch.
He walked the boundary with Frank, inspected the spring, and listened as Frank explained how close he was to losing everything.
“I’m not asking the bank to forgive the debt,” Frank told him. “I’m asking for a chance to get through this season.”
Thomas studied the water moving over the stones.
“There are things a bank can measure,” he said. “And there are things it can destroy without understanding their value.”
They negotiated for weeks.
Eventually, the bank agreed to restructure Frank’s obligations under a special covenant. The agreement protected a defined portion of the ranch from being transferred or sold without additional review. Any future enforcement against the protected acreage required the original instrument, verification of the recorded ownership terms, and approval through the bank’s legal process.
The arrangement was not charity.
Frank signed a repayment schedule, accepted restrictions on certain transactions, and agreed to maintain the watershed. The bank retained its legitimate rights under the loan, but it could not simply treat the entire ranch as unrestricted collateral.
Thomas signed the agreement.
Frank signed it.
Margaret witnessed the signing.
The document was stamped with the bank’s circular seal and entered into the institution’s records.
Before leaving, Thomas shook Frank’s hand.
“Keep your end of the bargain,” he said.
“I will.”
“And if anyone ever tells you this agreement doesn’t exist, ask them to find the original.”
Frank smiled faintly.
“You think someone will forget?”
Thomas looked toward the valley.
“I think people forget whatever becomes inconvenient.”
For years, the agreement remained little more than a precaution.
Frank paid the restructured loan. The ranch recovered slowly. He replaced old fencing, rebuilt the equipment shed, and expanded the herd when the market improved. Margaret planted wildflowers near the house and insisted on keeping a vegetable garden even when the weather made it difficult.
Then, in 2008, Margaret became ill.
The medical bills consumed much of their savings. Frank reduced the herd again and sold a small parcel of nonprotected land to cover expenses.
Margaret died two winters later.
Afterward, Frank stopped keeping the garden.
He continued running the ranch because it was the one thing that still connected him to the life they had built together.
He also continued keeping the original covenant.
It lived in a metal document box in his house, alongside his father’s papers, Margaret’s letters, and the records of every major transaction involving the property.
He had never expected to use it.
For years, he assumed the bank had maintained its own copy.
Then Victor Hale took over as manager.
Victor was not like his father.
He believed every problem could be solved by making the numbers look favorable. He considered old agreements an obstacle to efficiency and small borrowers a risk to be managed. He had once told a colleague that the future belonged to companies that could assemble land quickly and put it to productive use.
Granite Peak Development Group had approached the bank with an ambitious plan for the valley.
The company wanted access to a corridor of land near the highway. Its proposal included commercial buildings, storage facilities, and a distribution center. The project would require several parcels to be acquired before construction could begin.
The Walker property stood directly in the path of the proposed access route.
Without the protected acreage, the ranch could be valued, foreclosed upon, and transferred through ordinary procedures.
With the covenant in force, the process became more complicated.
The original agreement had to be examined. The protected boundaries had to be verified. The bank’s legal department had to determine whether any proposed transfer was permissible.
Victor saw the covenant as a delay.
Granite Peak saw it as a problem.
Someone at the company asked whether the bank could provide a clear title before the next financing milestone.
Victor promised that it could.
He began reviewing the Walker file.
The original covenant was not in the active digital folder. Its archival reference appeared in an older system, and the paper file had been moved years earlier during a records reorganization.
Rather than request a formal search, Victor relied on a brief note suggesting that the original document was unavailable.
He interpreted unavailable as irrelevant.
Then he made a second mistake.
He assumed no one would challenge him.
The foreclosure authorization was prepared, and a digital approval appeared under the name of a former executive who had once handled similar transactions. Victor told himself that the old approval could be verified later, after the transfer had begun.
But the signature was not legitimate.
The more he tried to move the transaction forward, the more his decisions depended on the assumption that nobody would examine the details.
That morning, when Frank walked into the bank, Victor saw only a poor rancher who had run out of money.
He did not see the original agreement.
He did not see Margaret’s signature as witness.
He did not see the promise his father had made.
And he did not imagine that the old man he ordered out of the lobby would be carrying the very document capable of bringing his carefully constructed plan to a halt.
Claire leaned over the paper.
“Mr. Walker,” she said, “may I examine this?”
Frank nodded.
She lifted the document carefully by its edges.
The embossed seal was consistent with historical examples stored in the bank’s archive. The paper showed signs of age. The handwritten signatures were clear enough for a qualified examiner to study.
But the most important detail was the covenant’s language.
The agreement did not erase Frank’s debt.
It did not grant him immunity from every legal claim the bank might have.
Instead, it placed specific conditions on the protected acreage and required an additional verification process before any transfer could proceed.
Those conditions had not been followed.
Claire looked at Victor.
“Did you review this covenant before approving the foreclosure?”
Victor’s eyes flicked toward the office.
“The document has not been authenticated.”
“That doesn’t answer the question.”
“I’m the manager here.”
“And the approval references a signature from someone who died years ago.”
Victor lowered his voice.
“You need to stop.”
Claire looked back at the original.
For thirty years, the agreement had sat quietly in a metal box, preserved by a man who believed that keeping a promise was as important as making one.
Now it had become the only thing standing between a family’s land and a transaction that might never have survived proper scrutiny.
Frank folded his hands over the top of his satchel.
“Your father understood the agreement,” he said to Victor.
Victor’s face hardened.
“Do not bring my father into this.”
“His signature is on it.”
“My father signed hundreds of documents.”
“Then you should have no trouble explaining this one.”
Victor stared at him.
The old rancher’s voice was not angry.
That made it worse.
There was no threat in it, no attempt to intimidate, no demand for revenge. Frank was simply asking a question that the manager should have asked himself before attempting to take the ranch.
Claire placed the document beside the foreclosure record.
Two signatures appeared on the screen.
One was the legitimate signature from the original agreement.
The other was the suspicious approval.
The differences were small enough to escape a casual glance, but significant enough to demand investigation.
Claire returned to the phone.
“Compliance,” she said, “I have the original covenant in front of me now. The foreclosure authorization appears inconsistent with its restrictions. I need an immediate hold on the transaction.”
Victor stepped forward.
“You cannot do that without my authorization.”
Claire looked him in the eye.
“I’m not authorizing anything. I’m reporting a material discrepancy.”
She gave compliance the file number and the name of the proposed buyer.
Then she added one final detail.
“The original document contains a signature from Thomas Hale.”
Silence followed on the other end of the call.
“Please preserve the record,” the compliance officer said. “Do not alter, delete, or move any related files. We will contact the bank’s legal department.”
Claire wrote down the instructions.
Victor stood beside her desk, motionless.
Frank watched the snow falling beyond the windows.
He had waited thirty years for the agreement to matter again.
He had not expected the moment to feel like victory.
It felt like opening a door into a room where everyone had been pretending there was nothing to see.
And behind that door, something much larger than a ranch loan was waiting.
PART 4 — THE PRICE OF A SIGNATURE
By ten o’clock, the bank lobby had become painfully quiet.
Claire had completed the initial compliance report. She had preserved the digital records, documented the discrepancy, and sent photographs of the original covenant to the bank’s legal department.
She had not accused Victor of a crime.
She had not declared the signature forged as a final finding.
She had done something more difficult.
She had made it impossible for the bank to pretend the question did not exist.
Victor paced between his office and the counter, occasionally checking his phone. Each time the screen lit up, he read the message and immediately turned it facedown.
Frank remained near the window, his satchel beside him.
He could have left.
Instead, he waited for someone with authority to explain why the bank had ignored the agreement.
At 10:14, Victor approached him.
“Mr. Walker, perhaps we should discuss this privately.”
Frank looked at him.
“We were discussing it privately when you told me to leave.”
“That was before I saw the document.”
“No. It was before you understood what it meant.”
Victor glanced toward Claire.
“I’m willing to review your account.”
“You were supposed to review it before trying to sell my land.”
“The foreclosure process has not been completed.”
“Then stop it.”
Victor exhaled through his nose.
“You have a delinquent loan. You understand that, correct?”
“I’ve never denied it.”
“The bank has obligations to its depositors.”
“So do I.”
Frank’s voice remained quiet.
“I owe money. I’m prepared to work out a legitimate repayment plan. But I won’t sign away land under an agreement you refuse to examine.”
Victor folded his arms.
“Your ranch is worth considerably more than your debt. If the property is sold, you could settle your obligations and retain some money.”
“And who gets the land?”
“That is not relevant to the loan.”
“It’s relevant to me.”
Victor’s mouth tightened.
“Sentiment does not change financial reality.”
“Neither does a forged signature.”
The manager looked away.
Frank could see the effort it took for Victor to remain composed.
For years, Victor had used his position to control the pace of difficult conversations. He spoke first, interrupted often, and made people feel that questioning him was a form of disrespect.
Now every attempt to redirect the discussion brought him back to the same point.
The signature.
The covenant.
The original document.
Claire approached them with a printed copy of the compliance report.
“The foreclosure is being placed on temporary hold pending review,” she said.
Victor turned sharply.
“By whom?”
“Compliance and legal.”
“You cannot suspend a transaction based on an unverified document.”
“They are suspending it because the bank has an original covenant that conflicts with the authorization. They’ll determine the next steps.”
“This is my branch.”
“And these are the bank’s records.”
For a moment, the two stared at each other.
Then Victor lowered his voice.
“You’re making a career-ending decision.”
Claire’s expression did not change.
“If the record is legitimate, the review will support you. If it isn’t, the review will protect the bank.”
Victor looked at Frank.
“You’re enjoying this.”
Frank shook his head.
“No.”
The answer was so immediate that Victor paused.
“I wanted thirty days,” Frank continued. “I wanted enough time to sell part of my herd and make a payment. I came here because I believed the agreement my father and yours signed still meant something.”
He looked down at the covenant.
“I didn’t come here to ruin anyone.”
Victor had no reply.
At 10:32, Claire received a call from the legal department. She listened carefully, asked two questions, and wrote several notes.
When she hung up, she looked at Frank.
“They need to verify the original document, the property boundaries, and the chain of title. They’re also reviewing the authorization and the proposed transfer to Granite Peak.”
“How long?” Frank asked.
“They haven’t given a final timeline.”
He nodded.
“Then I’ll wait.”
Victor let out a frustrated breath.
“You cannot expect the bank to suspend everything indefinitely.”
“I expect the bank to follow its own rules.”
Claire returned to her desk.
As she prepared the records for the legal team, another message arrived from compliance. It requested the earlier versions of the foreclosure file, including any deleted or superseded attachments.
Claire opened the document history.
There were three versions, not two.
The first contained the original loan information.
The second included the covenant reference and a note requiring the original instrument.
The third had been created six weeks earlier. It contained the authorization that allowed the foreclosure to proceed without the original.
Claire examined the timestamp.
The file had been modified late on a Friday evening, after the records department had closed.
The user account belonged to Victor.
She saved the information to the protected review folder and forwarded it to compliance.
She did not know whether the change had been made deliberately to bypass the covenant or whether Victor would claim it had been an administrative error. That was for the investigators to determine.
But she knew one thing.
The record had changed, and the change mattered.
Victor saw her finish the upload.
“What did you send?”
“The version history.”
His face tightened.
“That information is internal.”
“Yes.”
“You had no authority to distribute it.”
“I sent it to the department responsible for reviewing the transaction.”
“You’re supposed to work for the bank, not against it.”
Claire stood.
“I am working for the bank.”
Her voice was calm, but the words carried across the quiet lobby.
“If this foreclosure is valid, we should be able to prove it. If it isn’t, then stopping it is the only responsible thing to do.”
Victor stared at her.
“You think you know everything because you found an old piece of paper?”
“No,” Claire said. “I think the paper is important enough that we should find out what it means.”
At 11:05, the bank’s legal department requested a copy of the original covenant’s front and back. Claire photographed both sides under controlled lighting, recorded the document’s condition, and placed it in a protective sleeve.
Frank watched her work.
“Thank you,” he said.
Claire looked up.
“You don’t have to thank me for doing my job.”
“Maybe not. But I know what it costs when someone decides their job doesn’t matter.”
She considered that for a moment.
Then she returned to the paperwork.
Outside, the snow had begun to ease.
A gray pickup passed the bank windows, tires crunching over the road. Across the street, the diner’s neon sign flickered on despite the daylight.
Red Hollow looked exactly as it had an hour earlier.
But inside the bank, the balance of power had changed.
Victor was no longer the only person who could decide what happened next.
At 11:26, his phone rang.
He answered and stepped into his office.
Claire could not hear the caller, but she saw Victor’s expression change as he listened.
He stood rigidly beside his desk.
Then he said, “I told you the transaction was moving forward.”
A pause.
“No, the original document was not in the active file.”
Another pause.
His jaw tightened.
“I understand the deadline.”
He listened again.
Then he ended the call and remained still, staring at the glass wall.
Claire looked toward Frank.
“Was that Granite Peak?” she asked quietly.
Frank nodded once.
“I’d imagine so.”
“You knew they were involved?”
“I knew someone wanted the property.”
“Did they approach you directly?”
“Once. A representative came to the ranch last spring. He offered me more money than I’d ever seen in one place.”
“What did you tell him?”
“That I wasn’t selling the protected acreage.”
Claire glanced at the covenant.
“And then the foreclosure began.”
Frank’s eyes remained on Victor’s office.
“That’s the order things happened in.”
Claire understood the implication.
The bank’s relationship with Granite Peak did not prove wrongdoing by itself. Companies purchased land, banks recovered debts, and developers negotiated transactions every day.
But the sequence raised questions.
Why had the original covenant not been located?
Why had a restricted file been altered?
Why did the foreclosure authorization rely on a signature that did not appear authentic?
And why had the manager been so determined to prevent a review?
At noon, Victor emerged from his office carrying a folder.
He placed it on Claire’s desk.
“This is the complete loan file,” he said.
Claire examined the folder.
It contained the usual documents, but not the original covenant or the earlier versions of the authorization.
“I need the archive references as well,” she said.
“They’re in the system.”
“Then I’ll include them in the review.”
Victor looked at Frank.
“You have what you wanted. The foreclosure is on hold. I suggest you leave while we sort this out.”
Frank picked up his satchel.
“I’ll leave when I know the land is safe from an improper transfer.”
“You cannot stay in the lobby indefinitely.”
“I can wait for a reasonable answer.”
Victor’s face reddened.
“This is harassment.”
Frank looked at him for a long moment.
“No, Mr. Hale. Harassment is using your position to frighten someone into giving up something they have a right to defend.”
He adjusted the satchel strap.
“I’m just standing here.”
Claire looked down to hide the emotion rising in her face.
Victor had spent the morning making Frank appear small.
Now the old rancher stood in the center of the bank, neither shouting nor threatening, and somehow seemed larger than the man who owned the office.
The afternoon review would determine what happened next.
But the bank manager had already lost the one advantage he had relied on most.
No one in the room was willing to take his word for it anymore.
PART 5 — WHAT THE OLD DOCUMENT REVEALED
The formal review began two days later.
The snowstorm had passed, leaving the mountains bright beneath a cold winter sun. Roads were open again, and the town had returned to its usual rhythm.
Inside Red Hollow Community Bank, however, the Walker file remained under restriction.
The legal department had engaged an independent document examiner to assess the original covenant and the disputed electronic authorization. The property records were being checked against county archives, and the foreclosure transaction remained suspended.
Frank returned to the bank when requested.
He wore the same forest-green ranch coat, the same burgundy flannel shirt, and the same worn boots. The leather satchel hung from his shoulder, but he no longer carried it as if it contained his last hope.
It contained evidence.
Claire met him at the counter.
“Legal has reviewed the initial findings,” she said. “They’re still investigating the signature, but the original covenant appears consistent with the historical bank records.”
Frank nodded.
“What does that mean for the ranch?”
“It means the foreclosure cannot proceed as originally prepared. The bank has to resolve the covenant issue and determine the proper treatment of the protected acreage.”
“Can they still take the ranch?”
“They may have lawful remedies for the outstanding debt, depending on the loan terms and the final legal findings. But they cannot simply ignore the covenant.”
Frank absorbed that answer.
It was not a promise that everything would be easy.
It was an honest explanation of where things stood.
“That’s all I’m asking,” he said. “A fair process.”
Claire led him to a small meeting area near the glass-walled office.
Victor was already there.
His suit was still immaculate, but the confidence that had once defined him had weakened. He looked as though he had spent the previous two nights sleeping in short, uncomfortable intervals.
A senior compliance officer joined by telephone.
She explained that the document examiner had identified significant inconsistencies in the disputed authorization. The electronic signature could not be treated as verified, and the bank would not rely on it while the investigation continued.
The county records also supported the existence of the original covenant.
The protected acreage had been described in a recorded instrument, and the restrictions were not extinguished simply because the bank’s active file lacked the original paper.
Frank listened without interrupting.
Then the compliance officer asked whether he had any additional documents.
He opened his satchel and produced a second envelope.
Inside were copies of the original loan agreement, payment records, and a letter from Thomas Hale dated shortly after the covenant had been signed.
Frank had preserved it because Margaret had believed the letter belonged with the agreement.
The letter confirmed that the covenant was intended to remain part of the bank’s records and that any future transfer involving the protected acreage required additional legal review.
It did not prove every detail of the present dispute, but it provided valuable context.
The compliance officer requested a copy.
Claire scanned it and added it to the review file.
Victor stared at the letter.
“My father never mentioned this to me,” he said.
Frank looked at him.
“Maybe he thought he wouldn’t need to.”
“You’re saying he knew this would happen?”
“No. I’m saying he understood why he made the agreement.”
Victor looked away.
For the first time, he seemed to understand that the dispute was not simply about an old document. It was about a decision made by someone who had believed that financial institutions had responsibilities beyond maximizing the value of every asset they controlled.
The investigation continued over the following weeks.
The bank reviewed Victor’s access history, communications concerning the Granite Peak transaction, and the sequence of changes made to the foreclosure authorization.
Investigators also examined whether any other files had been altered in a similar manner.
The bank did not publicly accuse Victor of criminal conduct while the review was ongoing. He was removed from direct oversight of the affected transactions, and his authority over restricted property records was suspended pending the outcome.
Granite Peak was notified that the proposed transfer could not proceed until the title and covenant questions were resolved.
Its representatives objected, arguing that the bank had represented the property as available for acquisition. The bank responded that the transaction was subject to verification and that no final transfer had been completed.
The deadline passed.
The project did not collapse overnight, but the company had to reconsider its plans for the access route. The protected acreage could not be treated as ordinary, unrestricted land.
For Frank, the uncertainty remained difficult.
He still had a loan to repay.
The cattle still needed feed.
The ranch’s fences still required repairs, and the equipment shed still leaked when the snow began to melt.
Justice did not erase his bills.
But for the first time in months, Frank could plan without assuming that someone might take his land before he had a chance to defend it.
Claire kept him informed whenever she was permitted to do so.
She also began examining the bank’s older property records, discovering that several other legacy agreements had not been properly indexed after a software conversion years earlier.
Most were routine.
Some required clarification.
None could be assumed irrelevant merely because they were old.
The bank eventually established a formal review process for restricted land agreements. Any foreclosure involving a legacy covenant would require verification of the original instrument, a documented legal review, and independent authorization before a transfer could proceed.
Claire was asked to help lead the records remediation project.
It was a demanding assignment, but she accepted.
She had learned that careful work was not merely about keeping files organized. Sometimes, a single missing page could determine whether a person lost a home, a business, or a lifetime of labor.
One cold afternoon in early March, Frank received a call from the bank’s legal department.
The foreclosure had been withdrawn in its existing form.
The bank acknowledged that the authorization had not satisfied the requirements for proceeding against the protected acreage. The disputed signature remained under investigation, but the bank would not use it as a basis for enforcement.
The parties were invited to negotiate a revised repayment arrangement based on the legitimate loan balance and the verified collateral terms.
Frank sat at his kitchen table, listening.
Outside, snowmelt ran from the roof in steady drops. The ranch dogs lay near the stove, and a stack of unpaid bills rested beside a chipped coffee mug.
When the call ended, Frank remained still for a long time.
Then he looked toward the photograph on the wall.
Margaret was smiling in it, one hand resting on a fence post, her hair lifted by the wind.
“I told them,” he whispered. “I told them the agreement mattered.”
He did not imagine that she could hear him.
He simply needed to say it.
The negotiations took another month.
Frank provided updated financial records and a realistic projection of his income from cattle sales. The bank reviewed his ability to repay without requiring the sale of the protected acreage. Both sides obtained legal advice, and the final arrangement was documented carefully.
The new plan did not forgive the debt.
It gave Frank a manageable schedule, preserved the restrictions that remained legally enforceable, and required the bank to follow the proper process if circumstances changed.
Frank agreed to make regular payments and to provide updated financial information.
The bank agreed to honor the verified covenant and to correct its records.
Neither side got everything it might have wanted.
That was what made the agreement credible.
When Frank returned to sign the revised documents, Claire placed them on the walnut counter.
“Everything has been checked,” she said. “The terms match what legal approved.”
Frank read every page.
He asked two questions about the payment schedule and one about the treatment of the protected acreage. Claire answered each clearly.
Only after he was satisfied did he pick up the pen.
He signed.
Then he placed the pen down and looked at Claire.
“Thank you for reading what was actually there.”
She smiled faintly.
“You brought the document. I just made sure someone looked at it.”
“That’s more than I got the first time.”
Across the lobby, Victor stood near the entrance to his office.
He had not been dismissed at the time the revised agreement was signed, but his position remained under review. The bank’s investigation was ongoing, and his professional future was uncertain.
He approached Frank cautiously.
“Mr. Walker.”
Frank turned.
Victor seemed to struggle with the words.
“I owe you an apology.”
Frank waited.
“I should not have spoken to you the way I did. I made assumptions about you based on your appearance and your financial situation. That was wrong.”
Frank studied him.
“Why did you do it?”
Victor glanced toward Claire, then back at Frank.
“I thought I knew how the situation would end.”
“That’s not an answer.”
Victor swallowed.
“I thought you were desperate. I thought if I pushed hard enough, you would accept whatever the bank offered.”
“And the covenant?”
“I should have reviewed it properly.”
“You should have.”
Victor looked down.
“I can’t undo what happened.”
“No,” Frank said. “You can’t.”
For a moment, Victor appeared to expect something more. Perhaps forgiveness. Perhaps a reassuring statement that everything would be all right.
Frank offered neither.
Instead, he continued.
“You can make sure the next person who walks through that door gets treated like a human being before you look at his account balance.”
Victor nodded slowly.
“I understand.”
“I hope you do.”
Frank picked up his satchel and turned toward the exit.
Claire followed him to the door.
Outside, the air was sharp, but the sky had cleared. Snow still covered the rooftops, though the edges of the sidewalks had begun to darken where the ice was melting.
Frank paused on the steps.
For months, he had imagined that saving the ranch would feel like a victory parade. He had pictured himself driving home with a signed document, telling the cattle, the mountains, and Margaret’s photograph that the fight was over.
Instead, he felt tired.
Relieved, certainly.
But tired in the way a person feels after carrying something heavy for too long and finally setting it down.
Claire stood beside him.
“What will you do now?” she asked.
Frank looked toward the highway, beyond which the road led back to the ranch.
“I’ll fix the north fence before spring calving. Then I’ll repair the water trough by the lower pasture.”
She smiled.
“That sounds like a plan.”
“It’s the only kind I trust.”
He adjusted his hat.
“Plans you can work on with your own hands.”
Claire watched as he stepped down into the snow.
Before he reached his truck, she called after him.
“Mr. Walker?”
He turned.
“The bank is reviewing every restricted property file now. Yours wasn’t the only old record that needed attention.”
Frank nodded.
“Good.”
“You may have helped prevent this from happening to someone else.”
He looked back at the brick building.
“I hope so.”
Then he climbed into his truck and drove away.
The ranch was waiting.
There were bills to pay, fences to mend, and cattle to feed. There would be difficult seasons ahead, and no one had promised that the land would ever become easy to keep.
But it was still his to care for.
Weeks later, the independent review confirmed that the disputed foreclosure authorization contained irregularities serious enough that the bank could not rely on it. The investigation into how the signature had been created and used continued through the appropriate channels. The bank cooperated with the review, and Victor remained subject to its findings.
The full truth did not arrive in a single dramatic announcement.
It emerged through records, interviews, comparisons, and the patient work of people willing to ask questions that others preferred to avoid.
That was how the old secret finally came to light.
Not through a miracle.
Not through sudden wealth.
Through a document that had survived thirty years, a rancher who refused to abandon the truth, and a records specialist who understood that a discrepancy was not something to hide.
It was something to investigate.
On a bright morning in April, Frank stood beside the northern fence line.
The snow had retreated from the lower fields, revealing patches of dark earth and new grass. The spring water moved steadily over the stones, just as it had when his father first showed him the boundary.
Frank held the repaired fence wire in one hand and a pair of pliers in the other.
He had been working since sunrise.
A truck approached along the ranch road and stopped near the gate. A neighbor climbed out, carrying a thermos of coffee.
“Heard you finally got the bank sorted out,” the neighbor called.
Frank smiled.
“Got the paperwork sorted out.”
“Same thing, isn’t it?”
Frank looked toward the spring.
“No. Not always.”
His neighbor handed him the coffee.
For a while, they stood without speaking, watching the water pass through the rocks and continue down the valley.
Then the neighbor asked, “You ever think about selling the place after all that?”
Frank considered the question.
“Sometimes I think about how much easier my life would be if I didn’t have it.”
“That’s not the same as wanting to sell.”
“No,” Frank said. “It isn’t.”
He set the coffee on a fence post and returned to work.
He had not saved the ranch because he wanted to defeat Victor Hale. He had not fought because he expected recognition or revenge.
He had fought because his family had made a promise, because the land had value beyond its sale price, and because the truth should not become meaningless simply because it is inconvenient.
The ranch had never been a symbol of wealth.
It was work.
It was memory.
It was a responsibility passed from one generation to another.
And now it remained where it belonged.
At the bank, Claire continued the records review. She kept a copy of the revised process beside her desk, reminding herself that every file represented real people whose lives could be altered by a decision made in a quiet office.
Victor’s future remained uncertain. The investigation would determine his responsibility, and he would have to face the consequences of whatever the evidence established.
But the bank could no longer pretend that confidence was the same as correctness.
The next time a rancher entered the lobby wearing muddy boots and a worn coat, the staff would have a choice.
They could judge him by his appearance.
Or they could listen.
Frank hoped they would choose to listen.
Because he had learned something that winter.
A person’s worth cannot be measured by the condition of his coat, the balance of his account, or the number of people willing to stand behind him.
And a signature is only ink on paper until someone decides that the promise behind it deserves to be honored.
On the day Victor Hale told Frank Walker that he could not afford the bank, he believed he was speaking to a powerless old man.
He was wrong.
Frank had not walked into the bank carrying wealth.
May you like
He had walked in carrying the truth.
And sometimes, when the people in power have forgotten what they owe the people they serve, the truth is the most valuable thing in the room.